Doctors earn millions of dollars over the course of their careers and save only a small portion of it. That is not simply because most doctors lack financial literacy. It is also because of the personal circumstances each of us must face. A financial plan may become a shining light in the darkness of those circumstances.
To become a fully trained doctor, you first set up a path and a timeframe toward that goal. Creating a financial plan is just as important, and sometimes harder. Because finances are not always as predictable. They are tied to life itself and to the consequences of whatever life happens to bring.
Did I have a well-established financial plan as soon as I finished residency? Of course not. But I did make some financial decisions. I promised myself I would not incur credit card debt. I did not spend more than I earned, and I continued living modestly for a couple of years after graduation. The first thing I did, nonetheless, was stop sharing an apartment with strangers and rent my own place. I did not immediately buy a house. I did not buy a brand-new car. Instead, Fernanda, my 12-year-old Ford Taurus, became my mode of transportation. Nonetheless, I did pursue one of my dreams: becoming a backpacker doctor. I traveled throughout Latin America and Europe, combining most trips with volunteer work. Seventeen years later, those experiences continue to remain incredibly important to me. I do not consider them wasted money, because they enriched my life, gave me perspective, and created some of the most improbable connections. But did I save much money during this period? Certainly not.
Then, another stage of my life began. I met the girl who would later become my wife. And when we were ready, we had our beautiful daughter. When you have the responsibility of a family, your financial decisions revolve around this new reality. So, I moved to a family-friendly area. I bought a house. I made home improvements. And I spent thousands of dollars joyfully and willingly on the well-being of the people who became the center of my life.
Real physician voices, twice a week
Free, and one click to unsubscribe.
A few years later, after we had finally established many of the milestones of our future financial well-being, our little family went through some terrible situations. Our home was destroyed by Hurricane Ida. We subsequently became victims of a real estate scam. And we ended up dealing with people who took financial advantage of our situation.
Despite earning what most people would consider an excellent income, I found myself carrying substantial debt and wondering how someone who earns so much can still feel so financially constrained. But here is what changed everything. Regardless of the grim scenario, I did something that has helped me throughout my life, especially in the operating room. I did not panic. Because in my book, life happens. And when you are on the boat of apprehension, you must immediately row to calmer waters. With very careful planning, budgeting, and some sacrifices, we began to build again. Slowly. It took us years. But we made it because we adjusted our plans and our goals to our new circumstances.
In retrospect, had I possessed the financial literacy I have today, I would have done one thing radically differently: I would have started investing earlier than I did. I just did not understand one of the most exquisite words in financial English: compounding. The irony is that back then, I did not need to choose between living my life and investing for the future. I could have done both. And I did not count that as my career and income grew, so would my responsibilities and expenses.
Financial plans take different forms, and the form depends on the specifics of your life. Nonetheless, they all begin with the same two questions: What is your goal? And what is your timeframe for achieving it? I asked myself those questions when I finished training. I knew I had not entered medicine to retire five or ten years after residency, and I also knew that my goal was to reach financial independence. To me, that meant reaching the point where you work because you want to, because you still enjoy it, because working remains meaningful to you, not because you are financially trapped in a particular job. That distinction matters. I expect to continue working in some capacity for the rest of my life because I enjoy working. That is what financial independence gives you: choice.
If you have not done so, establish a financial goal. Give yourself a timeframe. Then, create a plan to achieve it and begin working toward it. Your goals may change. Your timeline may change as well. And that is fine. Just do not let your determination change. A good plan that evolves is much better than having no plan at all. Remember to live while you are building toward your goal. Travel if exploring matters to you. Build a family if that is what you desire. Spend money on experiences and people who genuinely enrich your life. Financial independence should not become another reason to postpone living. It should become a way to protect your ability to live according to your values.
My sincere wish is that you find the same kind of fulfillment that I have found, even with financial struggles and imperfect financial decisions. Because financial independence is not simply having enough money to stop working. It is having enough freedom to decide what kind of life you want to live. To me, that is the true meaning of financial independence.
Bruno Casanova is a minimally invasive gynecologic surgeon, department chair, physician leader, and writer in New York City. He is the founder of MD&D (Medicine, Dollars & Decisions), a free educational platform that helps residents, fellows, and early-career physicians navigate their careers, personal finances, and life in medicine.
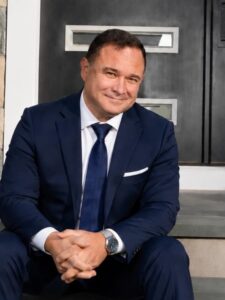
Drawing on his experience as a practicing surgeon and medical leader, Dr. Casanova recognizes that medical education prepares physicians to care for patients but often offers limited guidance on major career and financial decisions. Through MD&D, he helps bridge that gap by explaining career choices, job offers, employment contracts, physician compensation, relative value units (RVUs), productivity incentives, investing, and personal finances in clear, everyday language.
His writing also explores the human side of medicine, including professional identity, leadership, and the challenge of balancing professional and personal life. Rather than telling physicians what decisions to make, he offers education and perspectives that help them understand their options and make informed choices.
He shares free educational articles and a newsletter, along with podcasts, videos, and The Truth About RVUs Playbook. He is also on Instagram and Doximity.